

CardPointers: Maximize Rewards
CardPointers
- 4.5
- 283.00 Reviews
- 50.00K
- Downloads
- Free
- Price
Screenshots
CardPointers: Maximize Rewards Pros and Cons
Pros
- Tracks cards and rewards across multiple issuers in one place.
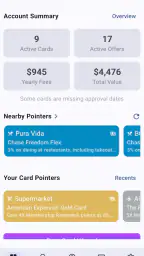
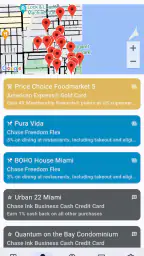
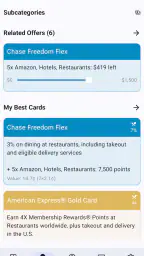
- Suggests the best card to use for each purchase category.
- Customizable reminders help prevent missed statement credits and benefits.
- Supports recurring expense tracking for subscriptions and regular bills.
- Useful tools help optimize points, miles, cash back, and welcome bonuses.
Cons
- Many advanced features require a paid subscription.
- Adding and updating cards can take time, especially with a large wallet.
- Recommendations depend on accurate merchant and category recognition.
- Some bank integrations may be limited or require periodic reconnection.
- The interface can feel overwhelming for users with only a few cards.
 Analysis by All-app
I usually approach credit-card reward apps with a little caution. Saving money sounds simple, but the useful part depends on how clearly the app explains its recommendations, what control it gives me, and whether it fits the way I already manage cards. After spending time with CardPointers: Maximize Rewards, I see it as a practical finance app for people who carry several rewards cards and regularly forget which one is best for a particular purchase.
Its central idea is straightforward: help me choose a card that can earn more cash back, points, or miles instead of relying on memory. That can be valuable in ordinary situations, such as paying for groceries, booking travel, ordering food, or making a large purchase. The app is free to install, although in-app purchases range from $4.99 to $279.99 per item, so I would pay attention to which parts of the experience are included before committing to anything.
How the app fits into everyday reward-card management
CardPointers is developed by CardPointers and sits in the finance category. It is rated for Everyone, which makes the presentation approachable, but the subject itself is more useful for adults who actively use credit cards and understand their own payment habits. The app was released on January 8, 2022, and the current version is 7.3.10, with Android support beginning at version 8.0.
The most useful way to think about it is as a decision aid rather than a replacement for a bank app. My bank app is still where I check transactions, balances, statements, and payments. CardPointers addresses a different problem: before I pay, which card should I reach for? That distinction matters because it prevents unrealistic expectations. It is not a complete personal-finance system, and I would not use it as my only place for account monitoring.
Its audience is already fairly clear from the concept. Someone with one flat-rate card may not gain much from maintaining another tool. Someone with several cards, rotating categories, travel benefits, or different rewards structures can have a harder time remembering the details. In that situation, a quick recommendation is more useful than keeping a spreadsheet or searching through old benefit pages.
The app has attracted over 50 thousand installs and holds an average rating of 4.5 from around 1.1 thousand ratings, with roughly 283 written reviews. Those figures suggest that the idea has found a real audience, but I would still judge it by whether its guidance matches my own cards and spending patterns. Reward programs change, and a high rating cannot guarantee that every recommendation will suit every wallet.
The first setup decision is how much information to share
The setup deserves more thought than the cheerful promise of maximizing rewards might suggest. Any reward assistant becomes more useful when it knows which cards I have and what kinds of purchases I make, but that also makes the information I enter more financially sensitive. I would begin with the smallest amount of information needed to test the workflow rather than immediately trying to recreate every detail of my financial life.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
This is one of the strongest practical habits for using the app responsibly: separate card selection from account access. If I only need help deciding between cards, I would first see whether manually adding those cards is enough for my needs. If a connected account or additional permission is presented, I would read the explanation and decide whether the convenience is worth the extra exposure. The right choice depends on the controls shown during setup, not on assumptions about what the app must be doing behind the scenes.
I also recommend checking every card after entering it. A recommendation is only as good as the card list and details behind it. If I have a co-branded card, an older product with unusual benefits, or a card whose reward rules recently changed, I would not blindly trust the first suggestion. I would compare the app’s choice with the issuer’s current terms before making a meaningful purchase.
Where the guidance can save real effort
The convenience becomes obvious in a realistic weekly routine. Imagine I am standing at a supermarket checkout with three cards: one that normally rewards groceries, one that offers a broad everyday return, and one tied to a temporary promotion. Instead of trying to remember category rules from memory, I can use the app to narrow the choice. The few seconds spent checking may prevent a small but repeated mistake across many shopping trips.
The same workflow helps with less predictable spending. A hotel booking, a streaming subscription, a taxi ride, or a purchase from a department store may not fit neatly into the categories I remember. CardPointers can be useful as a prompt to pause and identify the most suitable card before paying. That is a subtle strength: it changes reward optimization from a monthly review exercise into a decision made at the point of purchase.
Another non-obvious benefit is reducing mental clutter. People often collect cards for different reasons, then forget why each one exists. A recommendation tool can make a complicated wallet feel more manageable, particularly when I am traveling or shopping in a hurry. I do not need to memorize every earning rule if the app gives me a clear starting point.
Still, I would not treat any recommendation as automatic permission to spend. A higher reward rate is not a benefit if it encourages me to buy something unnecessary, carry a balance, or pay a fee that outweighs the return. My rule would be simple: choose the best card only after deciding that the purchase itself makes sense.
Comparing it with the usual alternatives
The most obvious alternative is a personal spreadsheet. A spreadsheet gives me complete control and can include annual fees, expiration dates, welcome offers, spending targets, and notes about benefits. It is also easy to customize. Its weakness is maintenance. If I forget to update a category or do not open it while shopping, it becomes an accurate-looking record that is no longer useful.
A notes app is faster for a short list, but it does not solve the memory problem very well. I might write “use Card A for groceries” and still wonder whether a temporary offer or a different merchant category changes the answer. CardPointers is more purpose-built for that decision, which is its main advantage over a plain note.
Issuer apps are essential for account management, but they generally focus on the relationship with one bank. They are not designed around comparing the cards in my entire wallet. CardPointers makes more sense when the difficulty is cross-card choice rather than checking a balance or paying a bill.
Reward blogs and online calculators can be excellent for learning. They often explain the reasoning behind a card strategy more thoroughly than a quick recommendation can. The trade-off is time and complexity. I would use those resources when deciding whether to keep a card or apply for a new one, while using CardPointers for the smaller decisions that happen during everyday spending.
Trust depends on visible choices, not assumptions
Because this is a finance app, I pay close attention to the moments where it asks for information, account access, or a purchase decision. The most reassuring workflow is one that makes those choices visible and understandable. I want to know what I am adding, why it is needed, and whether I can continue with a more limited setup.
I would also review the app’s account controls before relying on it regularly. That includes checking how to edit or remove cards, how to adjust preferences, and how to close the account if I stop using the service. These are not glamorous features, but they are important signs of user agency. A finance tool should make it easy for me to correct an entry or leave without feeling trapped.
Data-sensitive moments deserve extra attention. Entering a card name is different from granting access to financial accounts. Seeing a recommendation is different from authorizing a transaction. I would slow down whenever the app moves from organizing information to requesting a connection or presenting a paid option. The app can be useful without every convenience being necessary for every user.
I also prefer to keep notifications and promotional choices deliberate. If the app offers reminders or suggestions, I would enable only the ones that solve a real problem for me. Too many alerts can turn an otherwise helpful reward assistant into another source of financial noise. A good setup should make my decisions easier, not pressure me to check the app constantly.
What the paid options mean for a careful user
The free entry point is helpful because I can evaluate the basic idea before spending money. That matters here: the value depends heavily on how many cards I use, how often I optimize categories, and how much effort the app saves me. Someone with a simple wallet may find that the free experience is already enough, while a dedicated rewards enthusiast may consider additional tools worthwhile.
Since individual in-app purchases can reach $279.99, I would not tap through a purchase casually. I would first identify the exact feature or access period being offered, confirm whether it solves a problem I actually have, and compare the cost with the rewards I realistically expect to gain. A theoretical improvement is not the same as money in my pocket.
There is also a behavioral trade-off. Paying for a reward tool can encourage me to chase optimization even when the difference between cards is tiny. I would set a personal threshold: if changing cards saves only a negligible amount but adds friction, I would choose simplicity. The best system is not always the one that extracts every possible point; it is the one I can follow consistently without making mistakes.
Small workflows that make it more useful
My preferred workflow would be to review the wallet before a busy week rather than waiting until checkout every time. I would confirm that the cards I actually carry are represented, remove cards I no longer use, and note any issuer changes that could affect my choices. This reduces the chance of making a rushed decision with outdated information.
For travel, I would use the app as a planning companion, not as the final authority. Before booking a flight or hotel, I would compare its suggestion with the card’s current travel protections, fees, foreign transaction terms, and redemption value. The highest earning rate is only one part of the decision. A card with better practical coverage may be preferable even when another card appears stronger on points alone.
For household spending, the app can help create a shared routine, but I would avoid assuming that every family member will use it the same way. One person may care about cash back, while another values airline miles or simplicity. Agreeing on a few clear rules can be more effective than trying to optimize every purchase individually.
I would also use it as a learning tool. When the app points me toward a card, I would ask why that card is appropriate for the purchase. Over time, that can help me understand my own reward structure instead of becoming permanently dependent on prompts. If the recommendation conflicts with the issuer’s current terms, the conflict is a reason to investigate, not to force the purchase through.
Who should use it, and who should skip it
I think CardPointers is a good fit for someone who has multiple rewards cards, regularly forgets category bonuses, and wants a quicker alternative to maintaining a detailed spreadsheet. It is especially practical for people who make varied purchases and want a reminder at the moment when card choice matters.
I would be more hesitant to recommend it to someone who uses one main card, avoids tracking rewards, or wants a complete budgeting and bill-payment app. The extra layer may not justify the setup. It is also not the right tool for someone who expects reward optimization to compensate for carrying debt or spending beyond a budget.
Privacy-conscious users should make their own careful setup decision. I would start manually, inspect the visible account and data controls, and add only what I understand and need. Users who are uncomfortable with any financial information inside a third-party tool may prefer a spreadsheet or a simple note, even if those alternatives require more work.
Finally, experienced rewards users may find the app useful for speed but still want independent research for major choices. Applying for a card, paying an annual fee, transferring points, or booking expensive travel deserves more analysis than a quick in-app prompt. CardPointers can support that process, but it should not replace reading current issuer terms.
My cautious verdict
CardPointers succeeds because it focuses on a genuinely annoying problem: remembering which card is best before I pay. Its value is not in making finance exciting; it is in turning a cluttered set of reward rules into a more manageable choice. The free starting point makes it reasonable to test, and the broad audience reflected by its 4.5 average rating shows that the concept resonates with many users.
My recommendation comes with boundaries. I would keep my bank apps for balances and payments, verify important reward details with the issuer, and treat every connection, permission, notification, and purchase prompt as a choice rather than a requirement. I would also review the card list periodically, because an outdated setup can create false confidence.
The app is most valuable when it saves attention without taking away judgment. If I had a complicated wallet and wanted a practical reminder while shopping, I would give it a careful trial. If I wanted a minimalist financial routine or a full budgeting system, I would choose a simpler alternative. Used with those expectations, CardPointers is a useful companion for reward-card decisions, provided I remain the person making the final call.
Frequently Asked Questions
What is CardPointers: Maximize Rewards, and how does it work?
CardPointers: Maximize Rewards helps you choose the best credit card for each purchase so you can earn more points, miles, or cash back. After adding your cards, the app can show which card offers the strongest reward at a participating merchant or for a particular spending category. It also organizes card benefits, bonus categories, and available offers in one place.
Does CardPointers support both Android and iPhone devices?
CardPointers is designed for use across major mobile platforms, including iPhone and Android, although some features and integrations may vary depending on the operating system and device. Before downloading, check the current listing in the App Store or Google Play for compatibility requirements. Keeping the app updated is also recommended to receive the latest card databases and feature improvements.
Do I have to enter my bank login details or credit card numbers?
The app is primarily intended to help organize your existing cards and identify their rewards, rather than requiring you to provide online-banking credentials. You may need to enter card names or details so the recommendations are accurate, but you should review the app’s privacy policy before adding sensitive information. Never provide a password, security code, or banking login unless you fully understand why it is requested.
Can CardPointers help me remember annual fees, credits, and card benefits?
Yes. One of the app’s most useful purposes is keeping track of benefits that are easy to overlook, such as statement credits, spending bonuses, annual fee dates, and rotating reward categories. Depending on the card and the current version of the app, CardPointers may provide reminders or tracking tools. You should still verify redemption rules directly with your card issuer because terms can change.
Is CardPointers: Maximize Rewards free to use?
CardPointers offers free functionality, but certain advanced tools or premium features may require a subscription or in-app purchase. The exact pricing, trial availability, and included features can change over time and may differ between platforms. Check the store page and the in-app subscription screen before confirming payment. Also remember that the app cannot guarantee rewards, since earning rates depend on issuer terms, merchant coding, and account eligibility.


